Insights/Financing guide

Singapore home financing

Home loan rates, made easier to understand.

Use the monthly market snapshot, compare SORA and fixed-rate structures, and estimate repayments before speaking with your preferred banker.

The lowest advertised rate is not automatically the most suitable package. Cash-flow certainty, flexibility, lock-in terms and your likely holding period matter too.

A practical starting point

Financing is part of the property decision.

A home loan can run for decades, while a promotional package may last only a few years. I use financing numbers to help clients test affordability, holding power and downside—not to replace advice from a bank or mortgage specialist.

Before deciding, compare the complete package and ask what happens after the promotional or fixed-rate period ends.

Monthly reference

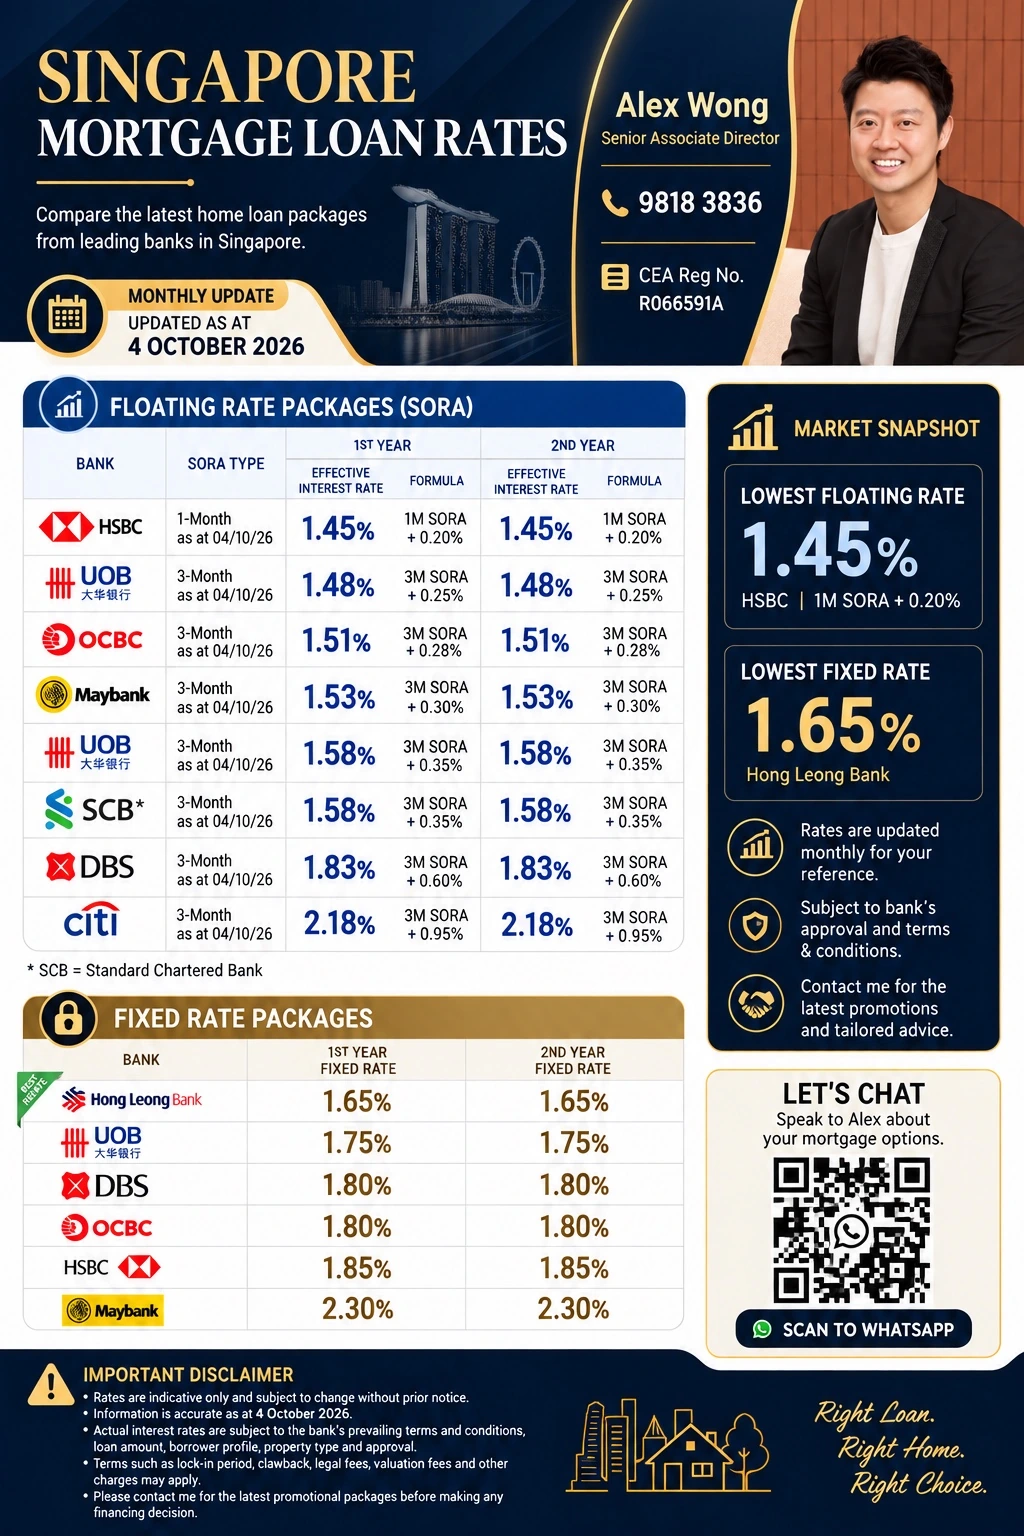
Singapore mortgage rate snapshot

A concise comparison of selected floating and fixed-rate packages shared with me for general market reference.

Latest uploaded edition4 October 2026

Always obtain a current quotation before applying. Rates and promotions can change at any time and the banks’ official source links were not supplied with this comparison. Ask your preferred trusted banker to confirm the exact, most up-to-date rate, lock-in period, fees, subsidies, clawbacks and eligibility.

Singapore mortgage loan rates updated 4 October 2026
Monthly mortgage market updateOpen or download PDF

Understanding the structures

SORA-based versus fixed-rate loans

Both can be sensible. The better fit depends on the loan terms, economic environment and how much repayment movement your household can comfortably absorb.

Market-linked

SORA-based package

SORA reflects the average rate of unsecured overnight Singapore-dollar transactions. A floating package commonly uses compounded 1-month or 3-month SORA plus a fixed bank spread.

Potential advantages

  • Can benefit when benchmark rates decline.
  • The bank spread is stated, making the pricing formula easier to see.
  • May suit borrowers with cash-flow room and tolerance for change.

Points to consider

  • Repayments can rise when SORA rises.
  • A reset period means changes may not appear immediately.
  • Lock-ins and clawbacks may still apply.

Payment certainty

Fixed-rate package

The interest rate is fixed for a stated period, commonly one to several years. After that period, the loan usually converts to a prevailing floating or board-rate structure unless repriced or refinanced.

Potential advantages

  • Predictable repayments during the fixed period.
  • Useful when rates may rise or household cash flow is tight.
  • Easier short-term budgeting for major life commitments.

Points to consider

  • The fixed rate may be higher than floating alternatives.
  • You may not benefit immediately if market rates fall.
  • Early redemption or refinancing can attract penalties.

When rates are rising or uncertain

A fixed package may be preferred by borrowers who value certainty and have limited room for repayment increases. The premium for certainty still needs to be weighed against lock-in restrictions.

When rates are expected to ease

A SORA-based package may appeal to borrowers willing to accept fluctuations in exchange for potential reductions. Rate forecasts can be wrong, so the loan should remain manageable if the opposite happens.

Personal circumstances matter

How life stage can influence the decision

01

First-home buyer

Renovation, marriage or childcare costs can make predictable repayments valuable. A fixed package may reduce near-term uncertainty; a SORA package may still suit a borrower with a strong cash buffer and flexible budget.

02

Upgrading family

Consider the overlap between sale and purchase, school expenses and temporary bridging needs. Certainty can help during a high-expense period, while flexibility matters if you may repay part of the loan after selling your existing home.

03

Property investor

Compare the loan against realistic rent, vacancy and maintenance—not only gross yield. An investor with diversified income and reserves may accept SORA movement; one with a tight cash-flow margin may prefer fixed repayments.

04

Approaching retirement

Income visibility and loan tenure often matter more than chasing the lowest headline rate. A shorter horizon or planned lump-sum repayment makes redemption conditions and lock-in expiry especially important.

Simple illustration

Suppose two households borrow the same amount. A dual-income couple with stable employment, a large emergency fund and a long holding horizon may be comfortable taking a SORA-linked package. A single-income household expecting education costs and preferring a fixed monthly budget may reasonably prioritise certainty—even if the fixed rate is slightly higher. Neither choice is automatically better; resilience under an unfavourable scenario is the real test.

Interactive estimate

Mortgage repayment calculator

Adjust three simple assumptions to estimate your monthly instalment and long-term interest cost.

Important: This is a simplified illustration only—not a loan eligibility, affordability, TDSR, MSR or approval assessment. It does not consider the borrowers’ number, ages, incomes, existing debts, CPF usage, loan-to-value limits, property type, residency, loan package features, fees or changes in interest rates. Actual repayments and permitted tenure may differ. Please verify your position with a bank or mortgage specialist before making a commitment.

2.50% p.a.
0.50%8.00%
25 years
1 year35 years

Estimated monthly repayment

—

Enter a loan amount to generate your repayment estimate.

Estimated total interest—
Estimated total payable—
If the rate were 1% higher—Stress-test result appears after an amount is entered.

Beyond the headline rate

Questions worth asking before choosing

Lock-inHow long, and what is the redemption penalty?
After the promotionWhat rate or formula applies when the special period ends?
RepricingCan you switch packages within the same bank, and at what cost?
SubsidiesAre legal or valuation subsidies subject to a clawback?
PrepaymentCan you make partial repayments without penalty?
Your bufferWould the loan remain comfortable if rates were 1–2% higher?

Need current package details?

Compare the complete terms, not only the headline rate.

I can connect you with someone who can verify current packages, explain the finer terms and assess your circumstances properly.

Request an introduction to a trusted, friendly and prompt mortgage specialist who I have a long term working relationship

Frequently asked questions

Useful points before you speak with a banker

Is a fixed-rate home loan always safer?+

It offers repayment certainty during the fixed period, but it may carry a higher rate, a lock-in period or less flexibility. What happens after the fixed period is equally important.

Does a SORA package fall immediately when market rates fall?+

Not necessarily. The package usually uses a compounded 1-month or 3-month SORA plus the bank’s spread, so the timing and size of a repayment change depend on the package’s reset mechanics.

Should I choose the package with the lowest headline rate?+

Not on that factor alone. Compare the lock-in period, bank spread, fixed-period expiry, repricing options, legal subsidy clawbacks, partial repayment rules and your likely holding period.

Is the calculator a loan-eligibility assessment?+

No. It is only a repayment illustration based on loan amount, interest rate and tenure. Banks apply additional eligibility, affordability, regulatory and property-specific criteria.

Back to all insights